
Getting a realistic valuation for your Canadian business before listing it for sale takes between four to eight weeks and involves gathering financial documentation, selecting the right valuation method for your industry, and working with a qualified professional appraiser. Without this upfront work, sellers risk leaving money on the table or watching their listing languish with an inflated asking price that scares off serious buyers.
The stakes are high. Canadian business owners who skip proper valuation often overprice by 20 to 40 percent based on emotional attachment rather than market realities. On the flip side, undervaluation means handing equity to the buyer, particularly problematic when property assets or real estate holdings comprise a significant portion of the business value. For companies with commercial real estate, warehouse space, or retail locations, the interplay between property valuation and business operations becomes even more complex.
A proper business appraisal goes beyond plugging numbers into a formula. It accounts for market conditions specific to your province, industry trends affecting Canadian businesses in 2026, the quality of your customer relationships, and whether your revenue model can survive without you at the helm. Real estate-related businesses face additional layers: lease terms, property appreciation potential, and how location-dependent your customer base truly is.
This guide walks you through the complete process, from organizing your financial records to challenging your appraiser’s assumptions. You’ll learn which valuation methods apply to your situation, what documentation Canadian buyers expect to see, and how to verify your numbers stand up to scrutiny before negotiations begin.
What You’ll Need: Essential Documents and Financial Records
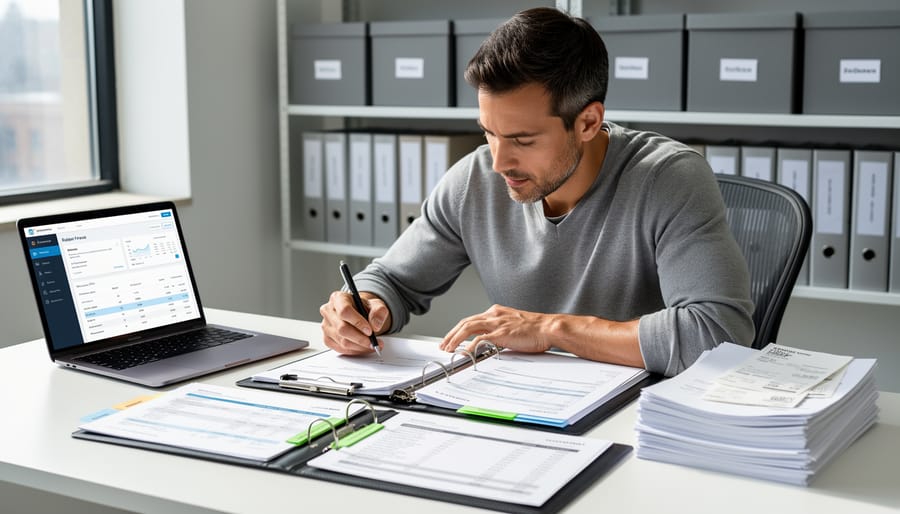
Before scheduling your first meeting with an appraiser, you’ll need to compile a comprehensive documentation package that proves your business’s financial health and operational structure. Most Canadian appraisers require multiple years of statements to establish patterns and trends rather than relying on a single year’s performance, which could be anomalous.
Financial statements form the backbone of any credible appraisal. Gather your complete income statements, balance sheets, and cash flow statements for the past three to five years. These documents reveal revenue trends, expense patterns, profitability margins, and how effectively you’ve managed working capital. Tax returns for the same period are equally critical because they provide the official, government-verified version of your financial story. Discrepancies between your internal financials and tax filings raise immediate red flags about accounting accuracy.
Your profit and loss statements show the granular breakdown of where money comes from and where it goes. Appraisers dig into these to identify discretionary expenses, owner compensation that might be above or below market rates, and non-recurring costs that shouldn’t factor into ongoing valuation calculations.
Asset inventories matter more than many owners realize. You’ll need detailed lists of equipment, machinery, vehicles, furniture, and technology, complete with purchase dates, current condition assessments, and depreciation schedules. For service businesses with minimal hard assets, intellectual property documentation becomes paramount, trademarks, patents, proprietary processes, software licenses, and brand materials all contribute to enterprise value.
- Financial statements (income statements, balance sheets, cash flow statements) for three to five years
- Corporate and personal tax returns for the same period
- Detailed profit and loss statements with expense breakdowns
- Complete asset inventories with depreciation schedules
- Customer contracts and recurring revenue agreements
- Lease agreements for premises, equipment, and vehicles
- Intellectual property documentation (trademarks, patents, proprietary systems)
- Organizational charts and key employee contracts
- Insurance policies and claims history
Customer contracts and recurring revenue agreements demonstrate the stability and predictability of your income stream. Long-term contracts with renewal clauses are worth significantly more than month-to-month arrangements. Lease agreements tell appraisers whether you’re locked into favourable terms or facing potential disruption, and whether those leases can transfer to a new owner.
Incomplete records don’t just slow down the appraisal process, they actively undermine credibility and can result in conservative valuations that leave money on the table. When appraisers encounter gaps, they typically assume the worst-case scenario rather than giving you the benefit of the doubt. Missing documentation forces them to apply larger risk discounts to their final valuation.
Red Flags and Warning Signs: When Appraisals Go Wrong
Spotting trouble before it derails your business sale starts with recognizing the red flags that plague poorly executed appraisals. The most fundamental mistake is hiring an appraiser without the proper credentials, specifically, someone who lacks the Chartered Business Valuator (CBV) designation from the Canadian Institute of Chartered Business Valuators. Your cousin who “knows numbers” or a generalist accountant without valuation specialization won’t cut it when buyers’ lenders and lawyers scrutinize the asking price.
Equally dangerous is the appraiser who applies a one-size-fits-all methodology without considering your industry’s unique characteristics. A tech company requires different valuation metrics than a manufacturing business, and a real estate brokerage has licensing and regulatory factors that generic formulas ignore completely. If your appraiser isn’t asking detailed questions about your specific sector, including compliance requirements, client concentration risks, or digital asset protection like cyber coverage for deals you’re heading toward an inaccurate number.
Timing matters more than many sellers realize. An appraiser who ignores current market conditions in your region and industry is working with obsolete data. In 2026, market dynamics shift rapidly, and an appraisal based on 2024 comparables or pre-pandemic multiples will either overprice you into obscurity or leave substantial money on the table.
The consequences of getting it wrong are severe. Overvaluation leads to months of stagnant listings, price reductions that signal desperation, and the loss of serious buyers who’ve already moved on. Undervaluation is arguably worse, you’ll sell quickly but realize years later that you surrendered hundreds of thousands in legitimate value because your appraiser missed key revenue streams or growth potential.
Step-by-Step: How to Obtain a Credible Business Appraisal
Step 1: Choose a Qualified Business Appraiser
Finding the right appraiser sets the foundation for an accurate valuation. In Canada, the gold standard credential is the Chartered Business Valuator (CBV) designation from the Canadian Institute of Chartered Business Valuators. CBVs complete rigorous training in valuation theory, financial analysis, and professional standards, qualifications that self-taught appraisers or generalists typically lack.
Start by searching the CBVI directory for practitioners in your province. Look for someone with experience in your specific industry, since valuation multiples and risk factors vary dramatically between, say, a property management firm and a manufacturing business. An appraiser who regularly values real estate brokerages will understand licensing considerations, commission structures, and market positioning in ways a generalist won’t.
During initial consultations, ask pointed questions: How many businesses similar to yours have they appraised in the past two years? Which valuation methods do they typically apply to your industry? Can they provide sample reports or client references? What’s their turnaround time and fee structure? Transparent answers signal professionalism; vague responses raise red flags.
Understand the difference between professionals. Business brokers estimate value to facilitate sales and earn commissions on transactions. Accountants handle financial statements but rarely hold valuation-specific credentials. Professional appraisers provide independent, defensible valuations following standardized methodologies. For a sale, you need the objectivity and credibility that only a qualified CBV delivers.
Choose someone whose expertise aligns with your business model and who communicates clearly about their process.
Step 2: Prepare Your Business for Assessment
Before the appraiser walks through your door, you need your business in review-ready condition. Think of this like staging a house for sale, presentation affects perception, and sloppy records signal risk to valuators.
Start with your financial housekeeping. Reconcile all bank statements against your accounting software, clear up any unexplained entries, and ensure revenue and expense categories are consistent across periods. If you’ve been mixing personal and business expenses, separate them now. Appraisers spot these inconsistencies immediately, and they’ll either discount your numbers or charge extra time to untangle the mess.
Document your customer base with specifics. Create a spreadsheet showing your top 20 clients by revenue, contract renewal dates, average purchase frequency, and customer tenure. If 60% of revenue comes from three clients, the appraiser needs to know, it’s a concentration risk that affects value. Conversely, a diverse base of recurring customers boosts your multiple.
Update your asset inventory beyond what’s on the balance sheet. List equipment with current replacement costs, software licenses and their renewal terms, and intellectual property including domain names, trademarks, and proprietary processes. Physical assets depreciate on paper, but a well-maintained fleet or recently upgraded equipment holds real value.
Address obvious operational gaps before the assessment. Outstanding supplier disputes, pending lawsuits, or key employees without contracts create valuation anchors that drag your number down.
Step 3: Understand the Valuation Methods Being Applied
Canadian business appraisers typically rely on three distinct valuation methods, often combining them to reach a defensible conclusion. Understanding these approaches helps you interpret the final number and ask informed questions during the review process.
Asset-based valuation calculates what your business owns minus what it owes. The book value method uses figures straight from your balance sheet, while the adjusted net asset approach recalibrates those numbers to reflect current market reality, updating equipment to fair market value, writing off obsolete inventory, and adjusting real estate to 2026 prices. This method works best for asset-heavy businesses or companies being sold for their tangible holdings rather than ongoing operations.
Income-based valuation focuses on future earnings potential. The capitalization of earnings method applies a multiplier to your normalized annual profit, while discounted cash flow projects several years of future income and converts those streams into present value. Appraisers favour income approaches for profitable, stable businesses where buyers are purchasing cash flow rather than just physical assets.
Market-based valuation compares your business to recently sold companies in your industry and region. This approach relies on actual transaction data, what buyers actually paid for similar businesses, typically expressed as multiples of revenue or EBITDA. It’s most reliable when sufficient comparable sales exist and your business fits established market patterns.
Most credible appraisals in Canada don’t pick just one method. Your appraiser will likely weight multiple approaches, giving heaviest consideration to whichever best reflects how buyers in your specific market make purchase decisions.
Step 4: Participate in the On-Site Assessment
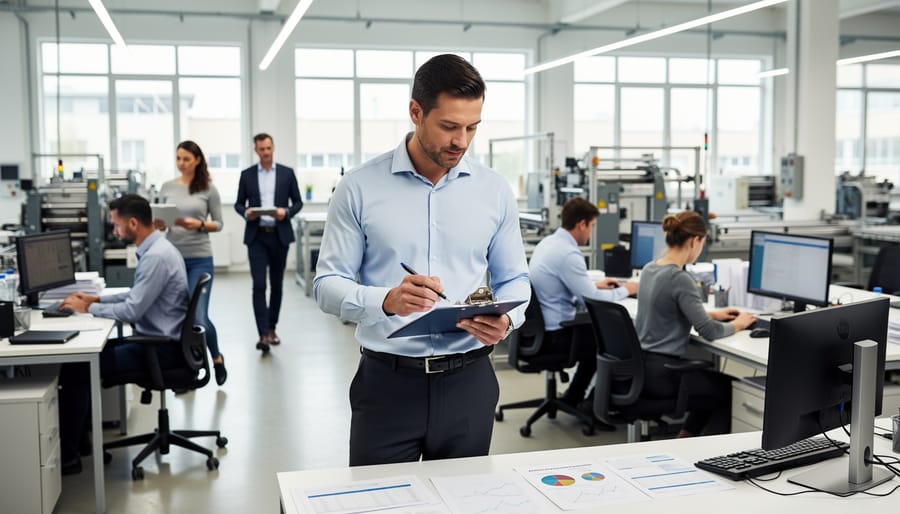
The on-site assessment is where your preparation meets scrutiny. Expect the appraiser to spend several hours, sometimes a full day, walking through your facility, observing operations, and asking probing questions about how the business actually runs.
During the facility tour, the appraiser will examine physical assets, workflow efficiency, equipment condition, and location advantages. They’ll note maintenance issues, space utilization, and any environmental concerns that might affect value. Let them see everything, including problem areas, hiding deficiencies now only creates surprises later that can derail negotiations.
Staff interviews help appraisers gauge operational depth and dependency risks. They’ll want to speak with key employees, managers, and sometimes frontline workers to understand institutional knowledge, succession readiness, and whether the business relies heavily on owner involvement. Brief your team beforehand, but encourage honest responses.
Operational discussions will cover customer concentration (how much revenue comes from your top five clients), contract terms, supplier relationships, and competitive positioning. Be prepared to explain growth trajectories, market threats, and strategic advantages with supporting data. Transparency builds credibility, acknowledge weaknesses while demonstrating how you’ve mitigated them. Appraisers value candor over perfection.
Step 5: Review the Draft Appraisal Report
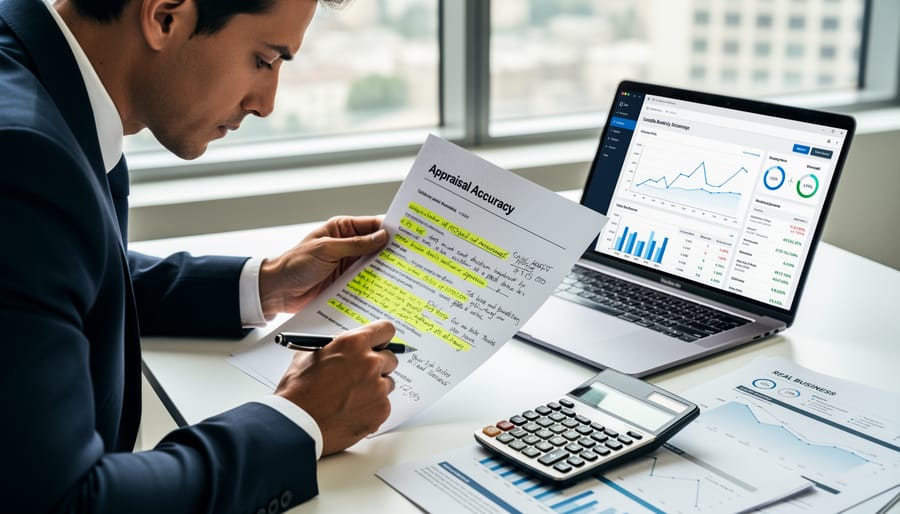
When your appraiser delivers the draft report, resist the temptation to flip straight to the final valuation figure. Start by reading the methodology section carefully, it explains why your business received its specific value. A credible Canadian appraisal report typically includes an executive summary, detailed financial analysis, description of valuation approaches used (asset-based, income-based, or market-based), normalization adjustments, and supporting schedules.
Check every factual detail against your records. Appraisers occasionally transpose numbers, misclassify expenses, or overlook revenue streams. One misplaced decimal in recurring revenue can swing your valuation by hundreds of thousands. Scrutinize the assumptions section closely. Does the growth rate assumption align with your actual performance? Are industry multiples current for 2026, or pulled from outdated data?
Question anything that seems off. Professional appraisers expect engaged clients to ask for clarification. If the report applies a 20% marketability discount but doesn’t explain why, ask. If comparable sales seem cherry-picked, request the rationale.
Pay attention to normalization adjustments, how the appraiser converted your historical earnings into maintainable cash flow by removing owner perks, one-time expenses, or below-market rent. These adjustments dramatically influence value and deserve your full understanding before accepting the final number.
Verifying Your Appraisal: How to Know If the Number Is Right
Even a professionally conducted appraisal deserves verification before you commit to a listing price. Think of validation as a safeguard against outlier assumptions, outdated comparables, or methodology choices that don’t reflect your specific market reality. Start by benchmarking the appraised value against recent sales of similar businesses in your province and industry. Business transfer databases, industry association reports, and transaction data from brokers can reveal whether your valuation sits within the typical range. If your appraiser valued your Calgary-based property management company at $1.2 million but comparable firms with similar unit counts and revenue sold for $800,000 to $950,000 in the past year, that gap demands explanation.
Consult with business brokers who actively list and sell businesses in your sector. Brokers see daily market conditions that appraisers, working from historical data, might miss. A broker can tell you whether buyers are currently paying premiums for certain characteristics your business has, or whether recent economic shifts have cooled demand in your niche. This reality check is particularly valuable in 2026’s fluctuating interest rate environment, where financing availability directly affects what buyers can pay. Ask brokers bluntly: “Based on what you’re seeing close right now, does this number make sense?”
Stress-test the valuation against buyer financing realities. Most Canadian business acquisitions involve some level of debt financing. If your appraisal suggests a $2 million value but the business generates insufficient cash flow to service a typical 70% loan at current commercial rates, buyers will struggle to close. Work backwards from what a qualified buyer could actually finance based on your EBITDA and debt service coverage ratios. A valuation that looks reasonable on paper but exceeds financing limits creates a pricing problem.
Separate emotional value from financial value during this verification process. You might have invested years building customer relationships, perfecting systems, or establishing a reputation, but appraisals measure what a third party will pay based on future cash flows and transferable assets. If the number feels low because it doesn’t account for your personal effort, that’s normal, not necessarily wrong. Conversely, if you’re surprised the appraisal came in high, don’t assume the appraiser made an error without investigating what market factors you might have underestimated.
Seek a second opinion when the appraisal falls significantly outside your expectations or when red flags emerge during your verification checks. A second qualified appraiser brings fresh methodology and assumptions. This is particularly warranted for businesses with unique characteristics, substantial real estate holdings, or those operating in rapidly changing sectors. The cost of a second appraisal often proves minor compared to mispricing your business by hundreds of thousands of dollars.
Use the verified appraisal strategically in your pricing approach rather than treating it as an absolute number. Most sellers list slightly above appraised value to create negotiation room, but staying within 5-10% of a credible appraisal keeps you in the realm of serious buyer consideration. If verification confirms the appraisal is solid, you can price confidently and defend your number during negotiations with data rather than hope.
Industry-Specific Considerations in Canadian Business Valuations
Industry valuations in Canada hinge on factors that generic appraisal formulas overlook. Real estate brokerages, for instance, carry value tied directly to recurring commission streams and agent retention rates rather than physical assets. Appraisers examining these businesses scrutinize historical transaction volumes, average commission percentages, and the stability of your agent roster. A brokerage with 20 agents who have been with you for five years commands a higher multiple than one with constant turnover, even if current revenues match. Provincial licensing requirements also matter, transferring a brokerage license in Ontario involves regulatory approvals that can delay closings, affecting perceived risk and therefore valuation.
Property management firms face different scrutiny. Here, appraisers focus on the quality and duration of management contracts rather than properties themselves. A portfolio of long-term commercial property management agreements with automatic renewal clauses justifies premium valuations, while month-to-month residential contracts introduce volatility that lowers multiples. The due diligence checklist buyers use for these acquisitions extends beyond financials to tenant satisfaction metrics and maintenance histories, elements appraisers increasingly weigh in 2026 valuations.
Mortgage brokerages and insurance agencies operate under regulatory frameworks that directly impact value. Appraisers must account for licensing costs, compliance infrastructure, and the transferability of client relationships under provincial regulations. A mortgage brokerage with E&O insurance claims in its history faces discounted valuations compared to clean-record competitors. Insurance agencies, meanwhile, see valuations shaped by carrier relationships and renewal rates, an agency with exclusive partnerships or 85 percent client retention rates will appraise higher than one dependent on transactional, single-policy clients.
Businesses owning real estate face dual valuation considerations. Appraisers separate operating business value from real property value, then assess whether the real estate enhances or constrains operations. A manufacturing business owning its facility debt-free adds significant balance sheet strength, but if that property sits in a declining industrial area with limited alternate uses, the asset may not command full market value in the overall business appraisal.
Common Questions About Business Appraisals in Canada
How much does a professional business appraisal cost in Canada?
Expect to pay between $5,000 and $15,000 for a comprehensive appraisal from a Chartered Business Valuator, with costs varying based on business complexity, industry, and revenue size. Simpler valuations for small businesses might start around $3,000, while complex enterprises with multiple locations or significant intangible assets can exceed $20,000.
How long does the appraisal process typically take?
A thorough business appraisal usually requires four to six weeks from initial engagement to final report delivery. This timeline includes document review, on-site assessment, analysis, draft report preparation, and your opportunity to review and request clarifications before the final version.
Will my appraisal information remain confidential?
Professional appraisers are bound by strict confidentiality agreements and professional ethics codes that protect your financial and operational data. You control who sees the final report, and appraisers will not disclose your business information to third parties without your explicit written consent.
Do business appraisals expire or need updating?
Most appraisals remain valid for six to twelve months under stable market conditions, but significant changes, such as major revenue shifts, new competitors, regulatory changes, or economic disruption, can quickly make valuations outdated. If your sale timeline extends beyond a year or market conditions shift substantially, consider requesting an updated valuation.
Beyond these basics, owners frequently wonder about the tax implications of their appraisal value. The figure in your appraisal report doesn’t determine your tax liability directly, but it does establish a defensible fair market value that can support your tax planning for sale and help justify your reported proceeds to the Canada Revenue Agency. Discrepancies between appraisal values and actual sale prices may trigger scrutiny, so working with both a qualified appraiser and tax advisor creates alignment between valuation and tax strategy.
Another common question concerns the difference between appraisals for selling versus financing purposes. Selling appraisals typically focus on market value, what a willing buyer would pay, while financing appraisals often emphasize liquidation value or asset coverage to satisfy lender risk requirements. If you obtained an appraisal for financing previously, it likely won’t serve your selling needs because the methodology and emphasis differ substantially. Banks want to know what they can recover if the loan defaults; buyers want to know what future cash flows and market position justify paying.
Finally, some owners ask whether they can use their appraisal to set the asking price directly. While the appraisal provides the foundation, your listing price might differ based on negotiation strategy, market timing, and how quickly you need to sell. The appraisal gives you the realistic range to work within, not necessarily the exact figure to put on your marketing materials.
A realistic business appraisal isn’t just a formality, it’s the foundation of a successful sale that protects your financial interests and positions your business competitively in the Canadian market. Without an accurate valuation, you risk either scaring away serious buyers with inflated pricing or leaving significant value on the table through underestimation.
The process you’ve followed, gathering comprehensive financial documentation, selecting a qualified appraiser with proper credentials, understanding the valuation methodologies applied to your specific situation, and verifying the results against market realities, provides a defensible number that stands up to buyer scrutiny and lender requirements. This systematic approach removes guesswork and replaces it with evidence-based confidence.
Professional appraisals facilitate smoother negotiations because both parties work from a credible baseline rather than emotional assumptions. Buyers see that you’ve done the homework, which builds trust and reduces the back-and-forth that delays closings. Lenders reviewing financing applications appreciate documented valuations from recognized Canadian appraisers, often speeding approval processes.
The investment in a qualified appraisal, typically a fraction of your business’s value, pays dividends through faster sales, stronger negotiating positions, and peace of mind that you’re making decisions based on market reality. As you prepare for this transition, remember that accurate valuations also connect to broader exit planning, including small business tax tips that maximize your after-sale proceeds. Start with the appraisal, and build your entire selling strategy on that solid foundation.