Detached Winnipeg home exterior in winter with icy roof eaves and wet street reflections near the foundation, suggesting weather and sewer backup risks.

How Much Does Home Insurance Cost in Winnipeg? (2026 Guide for New Homeowners)

Home insurance in Winnipeg costs between $1,200 and $2,500 per year for a detached home, with most homeowners paying around $1,000 annually or roughly $80 per month. If you’re shopping for coverage in Manitoba’s capital, you’ll find that your final premium hinges on four main variables: your home’s age and construction type, its replacement value, your claims history, and the coverage limits you select.
Key Takeaway: Winnipeg homeowners should budget $1,200-$2,500 annually for home insurance, carry at least $2 million in liability coverage, and ensure their policy …

Lakeside Quebec cottage at dusk with warm window lights reflecting on calm water, representing a second home property setting.

How Much Do Second Home Mortgage Rates Cost in Quebec? (2026)

Mortgage rates for second homes in Quebec currently start at 4.04% for insured five-year fixed terms and 3.40% for five-year variable rates, according to daily pricing from banks and mortgage brokers tracked by Ratehub as of mid-August 2026. But here’s what most buyers don’t realize upfront: those baseline numbers rarely apply to vacation properties or investment cottages the way they do to primary residences.
Second-home financing almost always costs more than your main residence mortgage. Three factors drive that premium: lenders consider non-primary properties higher risk, down payment requirements are typically …

A homebuyer and insurance broker meet in a living room over an open binder, conveying personalized home insurance guidance in Calgary.

How to Choose a Home Insurance Broker in Calgary: A Homebuyer’s Guide

Finding the right home insurance broker in Calgary takes three essential steps: verify their Alberta insurance license, confirm they represent multiple insurers (not just one), and ask specific questions about replacement cost coverage for your property’s unique risks. A qualified broker saves you money and protects your investment by comparing policies across carriers, something captive agents and direct insurers can’t offer.
Calgary’s real estate market in 2026 presents distinct challenges. Hailstorms cause millions in property damage annually, and the city’s mix of older character homes and new …

“Homeowner’s car parked in a suburban driveway in Ontario with the house entrance in the background, representing upcoming 2026 auto insurance changes.”

What Are Ontario’s 2026 Auto Insurance Changes (and How Do They Affect New Homeowners)?

Ontario auto insurance is undergoing its most significant structural overhaul in decades, shifting from mandatory bundled coverage to an à la carte system starting July 1, 2026. Under the new reforms, drivers will retain a smaller core of mandatory protections while gaining the ability to customize accident benefits, medical rehabilitation limits, and income replacement coverage based on their individual needs and budgets.
The timing matters for anyone holding both property and vehicle assets. If you’re a homeowner balancing mortgage payments with insurance premiums, these changes create an opportunity to realign your auto …

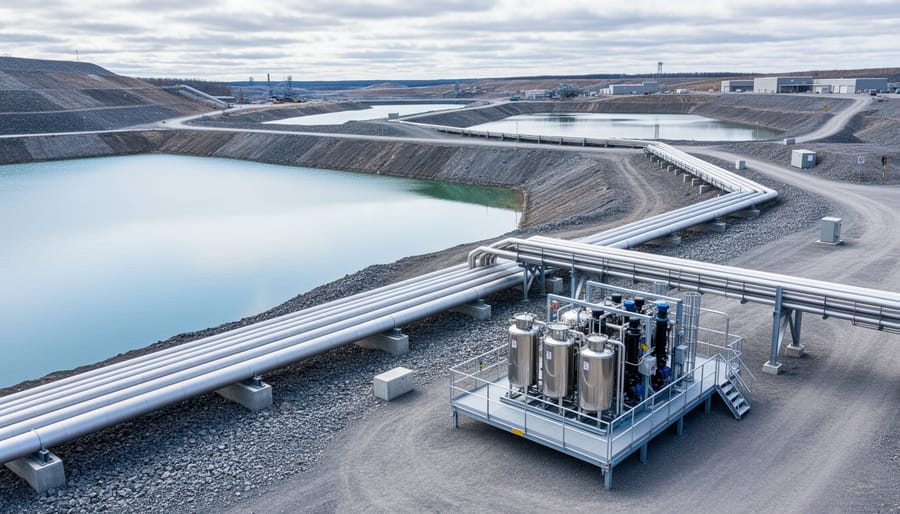
Canadian mining operations site featuring interconnected pipelines and a water treatment skid beside a tailings facility, suggesting integrated mine water management.

The Benefits of Integrated Water Treatment Systems for Canadian Mining Operations

Mine water management done in pieces creates its own problems. A treatment system handling acid rock drainage on the eastern side of a tailings facility, operated separately from a system managing process water on the western side, sharing no monitoring infrastructure and no operational data, produces a situation where the whole picture of the site’s water quality is never visible to anyone at one time. Integration is not just a technical preference. It is what allows a mining operation to actually know what is happening with its water.
1. What Integration Actually Means
An integrated mine water …

Financial advisor and real estate investor at a table with a small house model and calculator, Edmonton skyline and Walterdale Bridge softly blurred outside a large window, natural daylight.

Why Edmonton Real Estate Investors Need a Financial Advisor Who Actually Gets Property

Buying real estate in Edmonton is one of the biggest financial decisions you’ll ever make, and the tax implications, mortgage strategies, and investment structures can mean the difference between building wealth and leaving thousands on the table. Most financial advisors understand stocks and bonds, but properties require specialized knowledge about rental income taxation, capital gains strategies, leveraging equity, and how real estate fits into your broader financial plan.
A real estate financial advisor goes beyond basic investment advice. They understand how to structure property purchases to minimize tax liability, when …

Brass house key on stacked mortgage documents beside a small wooden house model on a desk, softly lit with a blurred office background and no readable text.

What Your 820 Credit Score Actually Gets You on a Mortgage Right Now

With an 820 credit score, you’re positioned to secure mortgage rates 0.5% to 0.75% lower than borrowers with average credit—a difference that translates to saving tens of thousands of dollars over your loan’s lifetime. Today’s top-tier borrowers are locking in rates that represent the most competitive tier lenders offer, but understanding exactly what you qualify for and how to leverage your exceptional credit requires knowing the current market landscape.
Your 820 score places you in the elite category where lenders compete aggressively for your business. Right now, the spread between excellent and good credit …

Mortgage loan officer consulting with a couple at a modern desk, with a small house model and house keys in focus under soft natural light, while a blurred office and city skyline appear in the background.

How Primary Mortgage Markets Shape Your Home Buying Power (And Why It Matters Now)

Every real estate transaction in America begins in the same place: the primary mortgage market. This is where lenders—banks, credit unions, and mortgage companies—originate new loans directly to homebuyers. Understanding this market isn’t just academic; it directly determines whether you can secure financing, what rate you’ll pay, and how competitive you’ll be as a buyer or investor.
The primary mortgage market operates as the first point of contact between borrowers and capital. When you apply for a home loan, you’re entering this market, where lenders evaluate your creditworthiness, set interest rates …

Diverse couple seated with a mortgage advisor at a dining table, reviewing paperwork next to a small house model, keys, and a calculator, with soft daylight and a blurred home interior in the background.

QM Mortgage Rules Are Changing Your Home Loan Options (Here’s What Actually Matters)

A Qualified Mortgage (QM) can determine whether you get approved for a home loan and at what interest rate. This federal designation, established after the 2008 housing crisis, sets strict lending standards that protect both borrowers and lenders from risky loan practices. When a mortgage meets QM requirements, it signals to everyone involved that the loan follows sound underwriting principles and the borrower has a genuine ability to repay.
The distinction matters because QM loans offer lenders legal protection from borrower lawsuits, which typically translates to better rates and terms for qualified buyers. Non-QM mortgages still …

Outstretched hand attempts to grab a swinging house key in front of a blurred upscale home at golden hour, suggesting a dream home slipping away due to tightening mortgage credit.

Why Your Dream Home Might Be Slipping Away (What Tightening Mortgage Credit Really Means)

Monitor the Mortgage Credit Availability Index (MCAI) monthly to gauge whether lending standards are loosening or tightening in real time. When the index rises above 120, expect increased competition among buyers and upward price pressure. When it drops below 100, prepare for slower transaction volumes and stronger negotiating positions for qualified buyers with substantial down payments.
Examine debt-to-income ratio requirements at your top three preferred lenders every quarter, as these thresholds directly determine your client pool size and purchasing power. A shift from 43% to 50% DTI acceptance can expand buyer qualification by…