Homeowner standing in front of a house with an insurance non-renewal notice, illustrating a contrast between a well-maintained side and a neglected side of the property.

Progressive Non-Renewal Notice: What Every Property Owner Must Know Before It’s Too Late

Receiving a progressive non-renewal notice from your insurance company signals a critical turning point in your property coverage that demands immediate attention. These formal notifications, typically issued 30-60 days before policy expiration, indicate your insurer’s decision not to renew your existing coverage due to specific risk factors or changing underwriting guidelines. For property owners and real estate professionals, understanding the implications of this notice is crucial – it’s not just a routine paperwork exercise but a potential threat to your property’s financial protection. Whether you’re a …

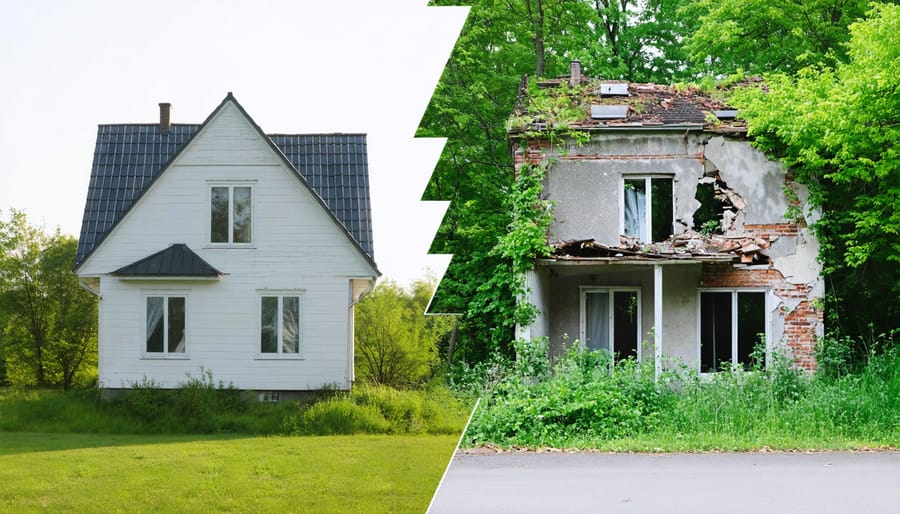
A comparison between a well-maintained property and a high-risk property with visible damages, representing the factors influencing insurance renewal decisions.

Why Your Insurance Company Won’t Renew (And What to Do Next)

Receiving an insurance non-renewal notice can shake any property owner’s confidence, but understanding this complex process empowers you to take control of your coverage future. Whether you’re a seasoned real estate investor or a first-time homeowner, insurance non-renewals represent a critical turning point that demands immediate attention and strategic action. These notices, while concerning, don’t necessarily spell disaster for your property protection plans.
Insurance companies can decide not to renew policies for various reasons – from changing risk assessments to shifts in their business strategy. …

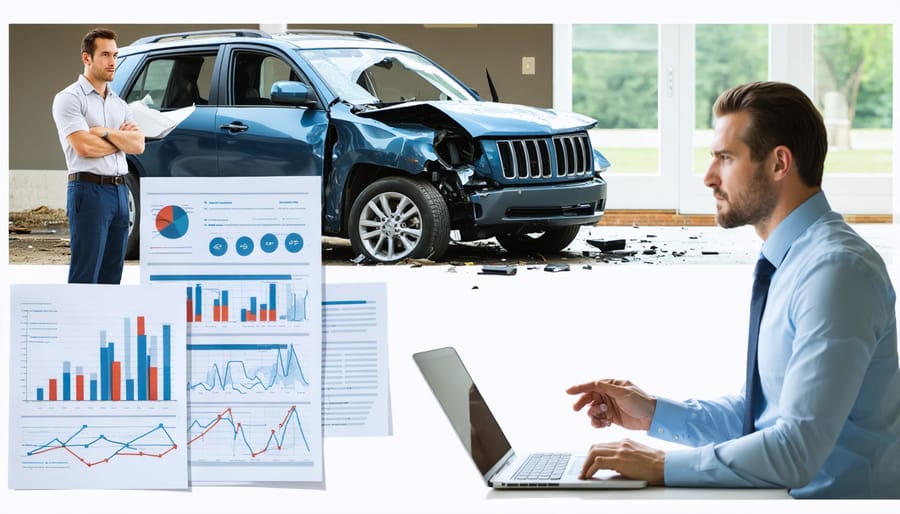
Split-screen image showing an insurance adjuster inspecting property damage, an analysis of an auto accident scene, and a review of medical documentation, highlighting the insurance claim processing journey and the importance of documentation and communication.

Insurance Claim Processing: What Really Affects Your Wait Time

Insurance claim processing times typically range from 2-6 weeks, though complex cases can extend to several months. Document gathering and prompt communication directly impact how quickly your claim moves through the system. Understanding this timeline helps set realistic expectations and allows you to plan accordingly.
Every insurance claim follows a distinct journey – from initial filing to final settlement. While standard auto claims might resolve in days, property damage claims often require detailed investigations, contractor estimates, and multiple adjuster visits. The complexity of your claim, the type of damage, and …

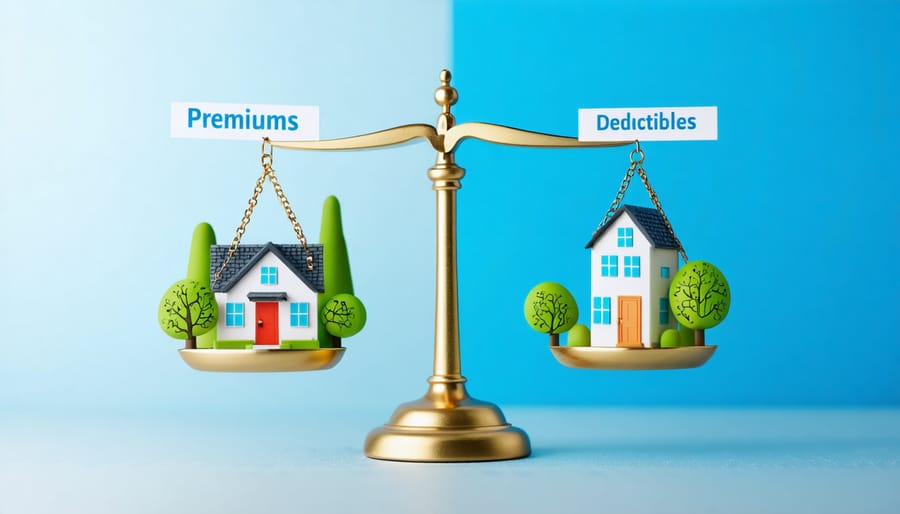
Balanced scale with the words "Premiums" and "Deductibles," with a house and commercial building in the background, illustrating strategic decision-making in property insurance.

How Insurance Deductibles and Premiums Impact Your Property Protection

Navigating the delicate balance between insurance deductibles and premiums can make or break your financial protection strategy. Every dollar you allocate between these two components directly impacts both your monthly expenses and potential out-of-pocket costs during claims. Understanding this relationship is crucial for achieving optimal insurance coverage while maintaining budget control.
Think of deductibles and premiums as two sides of the same financial shield – when one goes up, the other typically goes …

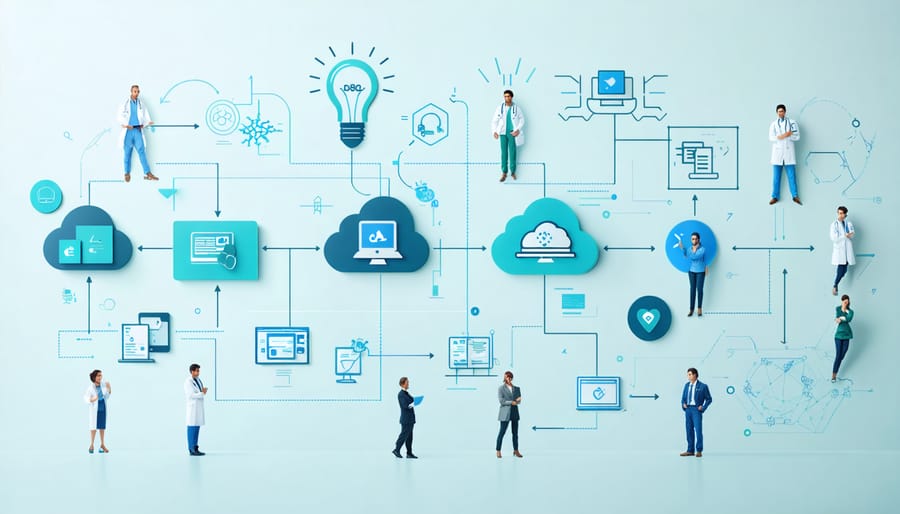
Conceptual illustration showing a streamlined health insurance claims process enhanced by digital technologies, featuring a flowchart with AI, blockchain, and cloud symbols.

How Health Insurance Claims Get Processed (A Real Timeline You Can Trust)

Navigating the maze of health insurance basics starts with understanding claims processing – a critical yet often misunderstood aspect of healthcare management. Every year, millions of claims flow through insurance systems, with processing times varying from a few days to several months depending on complexity and accuracy of submission.
Claims processing directly impacts both your healthcare access and financial well-being. When insurance companies receive claims, they …

A diverse group of self-employed professionals under a protective umbrella, representing workers' compensation insurance shielding them from work-related risks.

Self-Employed? Don’t Overlook This Crucial Insurance Coverage

Understand if workers’ compensation insurance is legally required for your self-employed business. State laws vary, but generally sole proprietors, independent contractors, and partners are exempt, while businesses with employees need coverage. Learn more about workers’ comp requirements by state.
Consider your occupational risks. Even if not mandated, workers’ comp provides valuable protection if you face on-the-job injury risks. Real estate agents showing properties, contractors doing repairs, and freelancers meeting …

A family and financial advisor discussing strategies for investing an insurance payout to secure a brighter future.

Transforming Tragedy into a Brighter Future: Investing Your Insurance Payout for Your Family

Pay off high-interest debts to free up cash flow for family goals. Establish a robust emergency fund covering 3-6 months of expenses. Invest a portion in low-risk, growth-oriented vehicles like index funds or real estate for long-term milestones. Consult a certified financial planner specializing in insurance payout for family planning to optimize your strategy.

…

Self-employed individual reviewing supplemental insurance policy at their desk, determined to secure financial protection against medical bills.

Self-Employed? Don’t Go Bankrupt Over Unexpected Medical Bills

Safeguard your financial well-being as a self-employed professional with supplemental insurance. While health insurance provides a basic safety net, supplemental coverage offers an extra layer of protection against unexpected medical expenses, disability, and loss of income. Explore critical policies like disability, accident, critical illness, and hospital indemnity insurance to identify the right mix for your unique needs and budget. Partner with a knowledgeable broker who specializes in…

A conceptual representation of financial strategy in managing the tax implications of insurance payouts, including symbolic elements of balance and interconnectivity.

Are Your Insurance Payouts Taxable? Here’s What You Need to Know

Evaluate the type of insurance payout you have received. Life insurance proceeds are generally tax-free, while payouts from health or accident policies might not be. Always check the details of your policy. Consult a tax professional to understand the specific tax implications of your payout. Tax laws can be complex and vary by jurisdiction and policy type. Utilize financial strategies to potentially reduce tax liabilities. Consider options such as spreading the payout over several years or reinvesting it in tax-advantaged accounts. Explore how to maximize your insurance payout through strategic financial planning, essential for …