
Securing homeowners insurance for your first home means gathering property details, comparing quotes from multiple carriers, and activating a policy before your closing date. Most lenders require proof of coverage as a condition of your mortgage, making this one of the final but essential steps in the homebuying process. The good news? Once you understand the core components like dwelling coverage, liability protection, and deductible structures, selecting the right policy becomes a straightforward checklist rather than a confusing maze of insurance speak.
First-time buyers often stumble in predictable ways. They accept the first quote without shopping around, misunderstand replacement cost versus actual cash value, or overlook coverage gaps that leave personal property and liability exposure unprotected. These mistakes aren’t just inconvenient; they can lead to out-of-pocket financial strain when claims arise.
This guide walks you through the practical steps: what documents and information you’ll need to request accurate quotes, how to decode policy components and endorsements, and the verification process to confirm your coverage meets lender requirements and protects your investment. By following a structured approach, you’ll avoid common pitfalls and secure coverage that fits both your budget and your risk profile before you hand over the keys to your new home.
What You Need Before Shopping for Homeowners Insurance
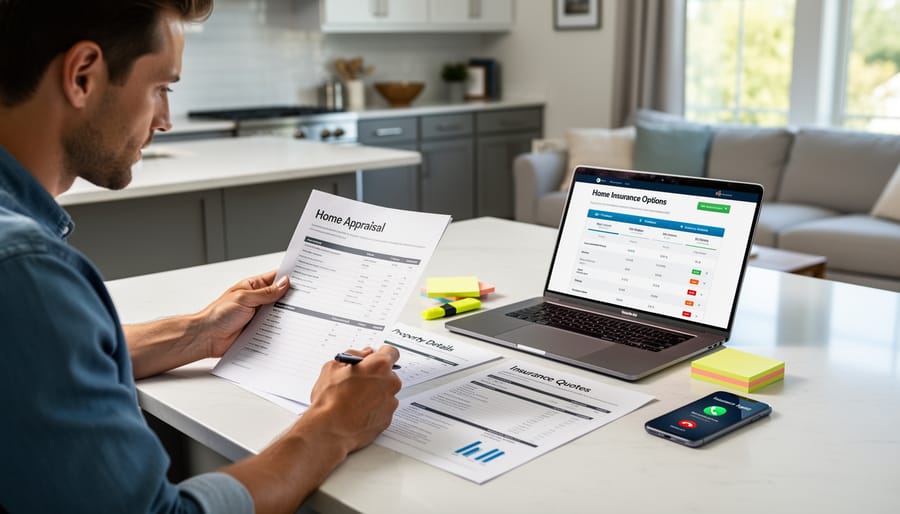
Before you request your first homeowners insurance quote, gather the right information so insurers can provide accurate pricing and appropriate coverage recommendations. Walking into this process prepared saves time, prevents back-and-forth delays, and helps you avoid surprises at closing.
Start with documentation about the property itself. You’ll need your home appraisal or the agreed purchase price, but understand that insurers care more about replacement cost, what it would take to rebuild, than market value. A house selling for $400,000 in a hot market might only cost $275,000 to reconstruct, and that difference matters for setting dwelling coverage limits.
Insurers will ask detailed questions about your home’s construction and condition:
- Year built and most recent major updates (roof replacement, electrical, plumbing, HVAC)
- Square footage and number of stories
- Construction materials (brick, vinyl siding, wood frame, concrete foundation)
- Roof type, age, and condition (asphalt shingle, metal, tile)
- Heating and cooling systems
- Number of bathrooms and overall home layout
These details directly affect your premium because they indicate risk. A 40-year-old roof signals higher claim probability than one replaced five years ago. Brick construction typically costs less to insure than wood siding in wildfire-prone areas.
Document any existing safety features: monitored security systems, smoke detectors, carbon monoxide detectors, fire extinguishers, or sprinkler systems. Many insurers offer discounts when these protections are already installed, sometimes reducing premiums noticeably.
Finally, contact your mortgage lender before shopping to understand their specific insurance requirements. Most lenders mandate minimum dwelling coverage amounts and require that they’re named on the policy as the mortgagee. Getting these requirements upfront prevents last-minute coverage adjustments that could delay your closing.
Understanding What Homeowners Insurance Actually Covers
A standard homeowners insurance policy bundles five core protections, and knowing what each one does, and doesn’t, cover will save you from expensive surprises down the line.
Dwelling coverage pays to repair or rebuild your home’s structure if it’s damaged by covered perils like fire, windstorms, hail, or vandalism. This extends to attached structures like a garage. Separate coverage for other structures detached sheds, fences, or standalone garages, typically runs as a percentage of your dwelling limit.
Personal property coverage protects your belongings (furniture, clothing, electronics) from the same covered perils. Policies usually cap this at a percentage of dwelling coverage, and they impose sublimits on categories like jewelry, art, or collectibles. If you own high-value items, standard limits won’t come close to replacing them.
Liability protection defends you if someone is injured on your property or you’re found legally responsible for damaging someone else’s property. It covers legal fees and settlements up to your policy limit. Medical payments coverage is a smaller, no-fault component that pays minor medical bills for guests injured at your home, regardless of who’s at fault.
Additional living expenses (ALE) reimburses hotel stays, meals, and other costs if your home becomes uninhabitable due to a covered loss. This keeps you from draining savings while repairs happen.
Now for the critical exclusions. Standard policies do not cover floods, earthquakes, sinkholes, or routine wear and tear. Water damage from backed-up sewers or sump pump failures often requires a separate endorsement. Surface water that seeps through foundations typically isn’t covered either. Mold and pest damage are excluded unless they result directly from a covered peril.
Understanding these boundaries before you compare quotes ensures you’re not shopping on price alone while leaving gaping holes in your protection.
Critical Warnings: Coverage Gaps That Catch New Homeowners
Most new homeowners focus on getting the lowest premium, but four critical coverage mistakes can leave you financially exposed when disaster strikes.
Dwelling Coverage Based on Purchase Price
The biggest trap is insuring your home for what you paid rather than what it costs to rebuild. Your purchase price includes land value and market conditions, neither matters if fire destroys your house. Rebuilding costs reflect current construction labor rates, material prices, and building code requirements that may differ dramatically from your home’s age or the real estate market. If you bought a $400,000 home where land accounts for $150,000, insuring for the full purchase price still leaves you $50,000 to $100,000 short if reconstruction runs higher than the remaining dwelling value. The red flag: your dwelling coverage matches your mortgage amount or purchase price exactly.
Flood Insurance Assumptions
Standard homeowners policies exclude flood damage entirely. Many first-time buyers assume flood insurance only matters near coastlines or rivers, but FEMA flood maps show risk zones extend far beyond obvious water bodies. Even properties outside high-risk zones can flood from heavy rainfall, storm surge, or overwhelmed drainage systems. Skipping flood coverage means paying out-of-pocket for water damage to your foundation, flooring, walls, HVAC systems, and belongings, often reaching tens of thousands of dollars. The consequence compounds if you lack the funds to make your home habitable again, because mortgage payments continue whether you can live there or not. Consider home disaster prep that includes proper flood risk assessment, not assumptions based on your neighborhood’s appearance.
Inadequate Personal Property Protection
Default personal property coverage typically equals a percentage of your dwelling coverage, often around half, but this may not reflect your actual possessions’ value. New homeowners often underestimate what they own until they inventory everything: furniture, electronics, appliances, clothing, tools, kitchenware. High-value items like jewelry, art, collectibles, or electronics face sublimits that cap what the policy pays per item or category, sometimes as low as a few thousand dollars total. Without scheduling these items separately or purchasing additional coverage, you’ll absorb the loss beyond those caps. The warning sign: you’ve never documented what you own or calculated replacement values.
Step-by-Step: How to Select Your Homeowners Insurance Policy
Selecting the right homeowners insurance requires a methodical approach that balances adequate protection with your budget. Here’s how to work through the process systematically.
- Calculate appropriate dwelling coverage using replacement cost estimators. Start by determining how much it would cost to rebuild your home from the ground up, not what you paid for it or its current market value. Use online replacement cost calculators that factor in your home’s square footage, construction materials, architectural features, and local building costs. Most insurers provide these tools, or you can hire an appraiser for precision. Add at least 20% above the base estimate to account for construction cost fluctuations and code upgrade requirements after a loss.
- Determine personal property coverage needs through a home inventory. Walk through each room and document your belongings, furniture, electronics, clothing, kitchen items, tools. Take photos and note approximate values. Most policies default to 50-70% of your dwelling coverage for contents, but verify this matches your actual needs. If you own jewelry, art, or collectibles, flag these items now since standard policies cap coverage for high-value categories.
- Choose liability limits based on your total assets and risk exposure. Basic policies often start at $100,000 in liability coverage, but if your net worth exceeds that amount, you’re vulnerable to lawsuits that could drain savings and retirement accounts. Consider your home equity, investment accounts, and future earnings. Many financial advisors recommend liability coverage equal to your total assets, and umbrella policies can extend protection beyond your base policy economically.
- Request quotes from at least three to five insurers, including bundling opportunities. Contact direct insurers, independent agents who represent multiple companies, and your auto insurance carrier. Ask each for identical coverage specifications so you can calculate coverage costs accurately across providers. Bundling home and auto policies typically unlocks discounts, but verify the combined price actually beats separate policies from different carriers.
- Compare policies beyond premium price alone. Line up the declarations pages side by side. Check dwelling coverage limits, deductible amounts (higher deductibles lower premiums but increase out-of-pocket costs after claims), and exclusions that might leave gaps. Review what endorsements each insurer includes standard versus charges extra for. A cheaper policy with restrictive terms often costs more after a claim than a slightly pricier comprehensive option.
- Review and understand the declarations page before signing. This document summarizes your entire policy in one or two pages. Verify your name and property address are correct, coverage limits match what you requested, deductibles align with what you can afford to pay, and the mortgagee clause lists your lender accurately. Misunderstandings here delay claims and closing.
- Coordinate your policy effective date with closing. Insurance must activate the moment you take ownership, not the day after. Provide your closing date to the insurer, and request the policy start at 12:01 AM that day. Obtain your declarations page and proof of insurance immediately to submit to your lender, since most won’t fund your loan without confirmation of coverage.
Each step builds on the previous one, creating a coverage foundation tailored to your specific property and financial situation rather than accepting default options that might leave you underprotected.
When to Add Endorsements and Riders
Standard homeowners policies leave gaps that can become expensive surprises. Endorsements and riders fill those holes, but not every new homeowner needs every add-on. Here’s when the extra coverage makes sense.
Scheduled Personal Property protects high-value items that exceed standard policy limits, jewelry, art, collectibles, musical instruments. If you own items worth more than your policy’s per-item cap (often a few thousand dollars), scheduling them covers full appraised value with no deductible. The test: would losing this item create financial hardship that your emergency fund couldn’t absorb?
Water Backup Coverage addresses sewer or drain backups, which standard policies exclude. If your home has a basement, older plumbing, or sits in a low-lying area prone to drainage issues, this endorsement prevents out-of-pocket cleanup and repair costs that can run into thousands.
Equipment Breakdown extends beyond basic coverage to include mechanical failures, HVAC systems, water heaters, appliances. New homeowners who’ve inherited older mechanicals or purchased homes with equipment nearing end-of-life should consider it. For those with newer systems or eco-friendly coverage protecting high-efficiency equipment, this becomes more valuable.
Identity Theft Protection bundles monitoring and recovery services. Evaluate this based on your existing credit monitoring rather than defaulting to the insurance version.
Home Business Coverage is essential if you run any business from your residence. Standard policies exclude business equipment and liability; even a home office with client visits creates exposure your base policy won’t cover.
Justify each endorsement by comparing the additional premium against the potential out-of-pocket cost and your likelihood of filing that type of claim.
How to Verify You Have Adequate Protection
Once your policy is in place, you need to confirm it actually protects you. Your declarations page is the roadmap, read every line to verify dwelling coverage reflects current rebuilding costs, not your purchase price or property tax assessment. Rebuilding costs account for construction materials, labor rates, and local building code requirements, which often differ significantly from market value.
Check that your lender’s name and loan number appear correctly in the mortgagee clause. An incorrect clause means claim checks get delayed or misdirected, creating headaches when you need repairs most. Confirm your coverage meets the minimum requirements spelled out in your mortgage documents, typically dwelling coverage at least equal to your loan amount.
Personal property and liability limits deserve scrutiny too. Walk through your home with your policy in hand and mentally tally whether your contents coverage would replace what you own. If you purchased scheduled endorsements for jewelry, electronics, or other valuables, verify those items appear with correct values.
Set a calendar reminder for one year from your effective date to review your coverage before renewal. Life changes fast for new homeowners, you’ll complete projects, buy furniture, add outbuildings. Adjust your coverage when you finish renovations worth more than a few thousand dollars, purchase high-value items, or if construction costs in your region shift noticeably. Contact your agent rather than waiting for renewal if major changes occur.
Common Questions About Homeowners Insurance for First-Time Buyers
Common Questions About Homeowners Insurance for First-Time Buyers
First-time homeowners often have similar questions about how insurance works in practice. Here are clear answers to help you navigate the process confidently.
When must my homeowners insurance be in place?
Your policy must be active on the closing date. Lenders require proof of coverage before finalizing the mortgage, so arrange your policy to start on the closing day to avoid delays.
Can I file a claim during my first year?
Yes, coverage begins immediately once your policy is active. Any covered loss that occurs after the effective date qualifies for a claim, regardless of how long you’ve held the policy.
How do claims affect my future premiums?
Filing a claim can increase your premiums at renewal, though the impact varies by insurer and claim type. Multiple claims within a few years may also make it harder to find coverage or lead to policy non-renewal.
Does my renters insurance transfer to homeowners coverage?
No, renters insurance and homeowners insurance are separate products. You’ll need to purchase a new homeowners policy and can cancel your renters policy once the new coverage begins.
If you need to adjust your policy mid-term, most insurers allow changes with prorated premium adjustments. Adding coverage typically takes effect immediately, while removing coverage may require advance notice.
When quoted rates feel unaffordable, explore options systematically. Raising your deductible lowers premiums but increases out-of-pocket costs for claims. Bundling home and auto insurance with the same carrier often unlocks discounts. Installing security systems, smoke detectors, or upgrading your roof can reduce rates. Some carriers offer payment plans that spread annual premiums across monthly installments, though this may include small fees.
Understanding whether insurance payouts taxable considerations apply can also help you plan financially for potential claims.
Review your policy annually, especially after major home improvements, significant purchases, or changes in your financial situation. Coverage that seemed adequate at closing may need adjustment as your circumstances evolve.
Selecting the right homeowners insurance isn’t just another closing task to check off, it’s the foundation of your financial protection as a new homeowner. You’ve walked through gathering essential information, understanding what standard policies actually cover, identifying dangerous coverage gaps, and following a systematic selection process. You’ve learned to evaluate endorsements based on your specific risks and verify that your final policy provides genuine protection, not just a certificate to satisfy your lender.
This isn’t a set-it-and-forget-it decision. Your coverage needs will shift as you renovate, acquire valuables, or as construction costs change in your area. Mark your calendar now to review your policy annually, ideally a month before renewal. Compare your dwelling coverage against current replacement cost estimates, reassess your personal property limits, and confirm your liability protection still aligns with your assets.
The few hours you invest in understanding and selecting appropriate coverage today protect both your property investment and your personal financial security for years to come. You’re not just buying insurance, you’re building a comprehensive risk management strategy that lets you enjoy homeownership with confidence.