
Generative AI risk management is the systematic process of identifying, assessing, and controlling the unique risks that arise when financial institutions use generative artificial intelligence models to make lending, underwriting, and insurance decisions. Unlike traditional AI systems that follow fixed rules, generative AI can create new outputs, predictions, and recommendations, which introduces uncertainty around accuracy, bias, transparency, and regulatory compliance.
For real estate professionals and property buyers, this matters more than you might expect. When a mortgage lender uses generative AI to assess your creditworthiness or an insurance company deploys it to calculate your homeowners policy premium, you’re dealing with a system that can produce novel risk assessments based on patterns it learned from vast datasets. That same capability that makes these tools powerful also makes them unpredictable. A model trained on historical mortgage data might inadvertently penalize borrowers in certain ZIP codes, or it could misinterpret property characteristics in ways a human underwriter would catch immediately.
The stakes are high. Poorly managed generative AI can lead to discriminatory lending practices, inaccurate property valuations, mispriced insurance policies, and regulatory penalties for institutions. For borrowers and homeowners, it can mean denied applications, higher rates, or coverage gaps you didn’t anticipate.
This article breaks down how generative AI risk management actually works in real estate finance, the specific components institutions must control, where these systems are currently deployed in mortgage and insurance underwriting, and what you should know whether you’re a professional implementing these tools or a consumer affected by their decisions.
What Generative AI Risk Management Means for Financial Services
Generative AI risk management is the structured process financial institutions use to identify, evaluate, and control the hazards introduced when AI systems create outputs, whether that’s a credit decision, a property valuation estimate, or an insurance premium calculation. Unlike traditional software that follows fixed rules, generative AI models produce novel responses by learning from patterns in data, which means they can also produce unexpected, biased, or incorrect results that directly affect borrowers and property owners.
Traditional AI risk management focused largely on narrow, predictable systems, think fraud detection algorithms or automated payment processing. Managing generative AI requires a fundamentally different approach because these systems don’t just execute predetermined logic; they interpret context, fill gaps in information, and generate recommendations that can look authoritative even when they’re wrong. When a lender uses AI risk prediction to assess whether someone qualifies for a mortgage, the institution needs safeguards against the model inventing risk factors, overlooking qualified applicants, or perpetuating historical lending discrimination.
- Generative AI
- Artificial intelligence systems that create new content, predictions, or decisions by learning patterns from training data rather than following explicit programmed rules.
- Risk Management Framework
- A formal structure of policies, procedures, and controls an organization uses to identify and reduce potential harm from AI systems throughout their lifecycle.
- Model Hallucination
- When an AI system generates plausible-seeming but factually incorrect information, such as citing non-existent property records or inventing market data.
- Bias Detection
- The process of testing whether an AI model produces systematically unfair outcomes for certain groups, such as denying mortgages more often to applicants from specific neighborhoods.
- AI Governance
- The organizational oversight, accountability structures, and decision-making processes that ensure AI systems serve their intended purpose without causing unacceptable harm.
In real estate finance and insurance, these risks translate directly to dollars and fairness. A property insurer relying on generative AI to set premiums needs controls to prevent the system from overcharging homeowners in certain zip codes based on proxy discrimination. A mortgage lender must ensure its AI doesn’t fabricate income verification details or misinterpret self-employment documentation. The stakes are high: poor risk management can result in regulatory penalties, lawsuits, reputational damage, and genuine harm to people trying to buy homes or protect their property investments.
How Generative AI Risk Management Works in Underwriting
Pre-Deployment Testing and Validation
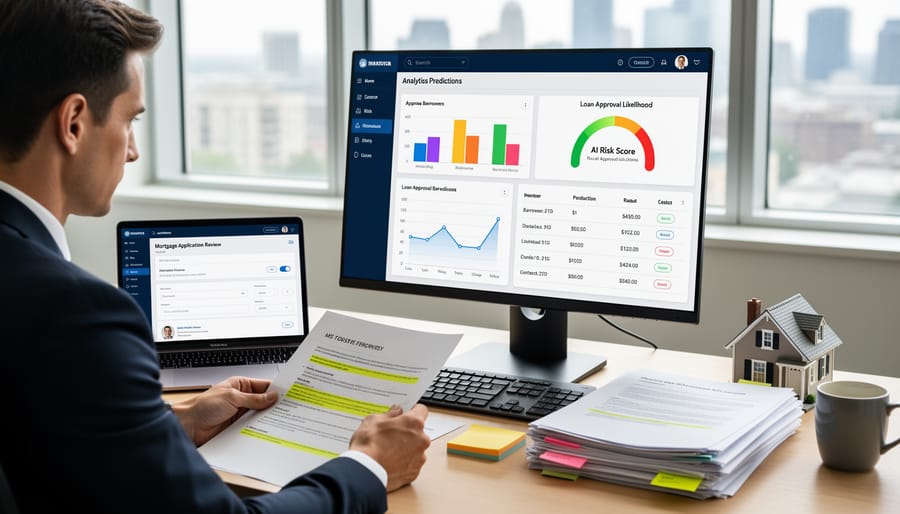
Before a lender deploys a generative AI system to review mortgage applications or assess property risk, the model goes through rigorous pre-deployment testing designed to catch problems that could harm borrowers or expose the institution to regulatory penalties. Testing begins with accuracy validation, running the AI through thousands of historical loan applications or insurance claims where outcomes are already known. If the model approves loans that defaulted or flags low-risk properties as high-risk, developers recalibrate before launch.
Bias testing is equally critical. Teams feed the AI applications from diverse demographic groups and geographic areas, then analyze whether approval rates, interest rate recommendations, or risk scores vary unfairly by race, gender, neighborhood, or property type. A model that consistently rates homes in majority-minority zip codes as higher risk, even when creditworthiness and property condition match comparable areas, fails the bias test and requires retraining.
Financial institutions also establish performance benchmarks: minimum accuracy thresholds (often 90% or higher for loan decisions), maximum false-positive rates for fraud detection, and acceptable margins of error in property valuation estimates. Only models that meet these standards and pass compliance reviews move into production, with documentation retained for audits.
Real-Time Monitoring and Human Oversight
Once a generative AI system goes live in underwriting, lenders and insurers deploy continuous monitoring dashboards that track thousands of decisions daily. These systems flag anomalies, like sudden spikes in denial rates for specific zip codes, unusual property valuations, or predictions that deviate sharply from historical patterns. When the AI recommends rejecting a mortgage application or quoting an unexpectedly high insurance premium, alerts route the case to human underwriters who can access the AI’s reasoning, review the applicant’s full file, and override the decision if it contradicts their professional judgment or local market knowledge.
This human-in-the-loop design is central to effective model risk management ensuring that no borrower gets denied or overcharged solely because an algorithm misread their situation. Senior underwriters typically review a sample of AI-approved decisions too, checking for patterns the system might miss, like approving loans on properties with hidden flood risks or underestimating claims exposure in aging neighborhoods. The goal isn’t to slow down automation but to catch errors before they reach customers, preserving both accuracy and fairness in high-stakes financial decisions.
Ongoing Audits and Model Updates
Financial institutions don’t just deploy generative AI models and walk away, they treat them like living systems that need continuous care. Regular audits happen on fixed schedules, typically quarterly or biannually, where independent teams review a sample of AI-driven underwriting decisions. They’re checking whether the model still performs accurately, whether it’s treating similar applicants consistently, and whether any new patterns of bias have emerged as market conditions shift.
When property markets change, interest rates spike, neighborhoods gentrify, climate risks escalate, yesterday’s training data becomes less relevant. Lenders retrain their models using fresh data that reflects current conditions, recalibrating how they assess home values, borrower risk, or insurance claims likelihood. This prevents the AI from making decisions based on outdated assumptions about what makes a property a good investment or a borrower creditworthy.
Every audit and update gets documented in compliance logs that regulators can inspect. Banks and insurers maintain detailed records showing what they tested, what they found, and how they responded, creating an evidence trail that proves they’re actively managing the technology rather than letting it run on autopilot.
Core Components of an AI Risk Management Framework
A comprehensive risk management framework for generative AI in financial underwriting rests on five interconnected pillars that work together to protect both institutions and consumers. These components form the foundation that determines whether an AI system operates fairly, transparently, and within regulatory boundaries.
Data governance establishes the quality and integrity of information feeding AI models. In mortgage underwriting, this means verifying property valuations come from reliable sources, income documentation meets regulatory standards, and historical default data accurately represents diverse borrower populations. Poor data quality leads to flawed predictions, garbage in, garbage out. Strong governance includes version control for training datasets, documentation of data sources, and regular audits to catch errors before they influence lending decisions.
Algorithmic transparency ensures human underwriters and compliance teams understand how the AI reaches its conclusions. Rather than accepting a black-box recommendation to deny a home loan, institutions need systems that explain which factors drove the decision, debt-to-income ratio, property location risk scores, or credit history patterns. This explainability becomes crucial when applicants challenge decisions or regulators investigate potential discrimination. The best frameworks combine automated explanations with documentation that non-technical stakeholders can understand.
Bias mitigation actively hunts for and corrects unfair patterns in AI recommendations. Testing protocols compare approval rates across protected classes, analyze whether certain ZIP codes face disproportionate denials, and flag models that recommend higher insurance premiums for properties in historically redlined neighborhoods. This pillar requires continuous monitoring because bias can creep in through training data, feature selection, or unexpected correlations the model discovers. Some lenders pair AI systems with smart sensors and third-party data to cross-check property risk assessments against physical conditions rather than demographic proxies.
At the operational level, effective frameworks organize around five core pillars:
- Data quality controls that validate sources, audit accuracy, and maintain consistent standards across training datasets
- Explainability mechanisms that translate AI recommendations into human-readable factors and document decision pathways
- Fairness safeguards that test for discriminatory patterns, monitor outcomes across demographics, and trigger alerts when disparities emerge
- Compliance documentation that maps AI decisions to lending regulations, maintains audit trails, and provides evidence for regulatory reviews
- Escalation procedures that route questionable AI recommendations to human oversight and establish clear protocols for overriding automated decisions
Regulatory compliance ties the framework to legal requirements. Financial institutions must document how their AI systems comply with fair lending laws, data privacy regulations, and industry-specific rules for mortgage and insurance underwriting. This pillar includes maintaining audit trails, preparing for regulatory examinations, and updating systems when new rules emerge. Compliance teams review AI-generated underwriting reports the same way they’d examine human decisions, looking for red flags that could trigger enforcement actions.
Incident response protocols prepare institutions for when something goes wrong, an AI model starts denying qualified applicants, generates hallucinated property data, or violates a regulation. These protocols spell out who investigates, how quickly the system gets pulled offline, how affected applicants get notified, and what remediation looks like. The difference between a contained incident and a full-blown crisis often comes down to having clear procedures ready before problems surface.
Where Generative AI Risk Management Applies in Property Finance
Mortgage Lending and Home Loan Underwriting
When a lender’s AI system reviews your mortgage application, risk management frameworks work behind the scenes to catch errors that could wrongly reject qualified borrowers or approve risky loans. These controls test whether the AI treats urban condos differently than rural properties, or whether it assigns lower creditworthiness scores to specific zip codes without legitimate reasons. Pre-deployment audits check for redlining patterns, situations where the algorithm systematically denies loans in certain neighborhoods based on demographics rather than actual default risk.
Real-time monitoring flags decisions that fall outside normal parameters. If the AI suddenly rejects applications in a particular price range or property type at unusual rates, human underwriters investigate before those denials become final. Similar oversight appears in AI property claims processing, where automated systems need guardrails against systematic bias. Regular audits compare AI approval rates across protected classes, ensuring the model doesn’t create disparate impact even when individual decisions seem reasonable in isolation.
Property and Title Insurance Risk Assessment
Property insurance providers use generative AI to analyze satellite imagery, weather patterns, historical claims data, and property characteristics to predict flood risk, fire hazards, and structural vulnerabilities. Risk management frameworks here focus on validating these predictions against actual claims history, if an AI model systematically overestimates risk in older neighborhoods or underestimates wildfire exposure in certain ZIP codes, it creates affordability problems and coverage gaps. Insurers implement geographic bias testing to ensure algorithms don’t penalize properties based on redlining-era patterns or demographics rather than genuine hazard assessment. Title insurance presents different challenges: AI systems scan public records to identify liens, encumbrances, and ownership disputes, but generative models can occasionally hallucinate nonexistent title defects or miss legitimate claims. Effective oversight requires human title examiners to verify AI findings before denying coverage or charging higher premiums, ensuring property coverage decisions reflect actual risk, not algorithmic errors.
Commercial Real Estate and Investment Analysis
Commercial real estate investors increasingly rely on generative AI platforms that analyze thousands of data points, vacancy rates, demographic shifts, zoning changes, infrastructure projects, to forecast returns and identify opportunities. These systems can spot patterns humans miss, but they also introduce unique risks that demand careful management.
Risk controls start with validating training data quality. AI models trained on incomplete or outdated transaction records might recommend industrial properties in declining logistics corridors or overvalue retail spaces without accounting for e-commerce impacts. Investors need assurance that the underlying data reflects current market realities, not historical patterns that no longer apply.
Stress testing matters here. Before trusting an AI’s investment recommendations, firms run scenarios testing how the model performs during economic downturns, interest rate spikes, or regional market crashes. A system that only learned from bull markets could catastrophically misjudge downside risk.
Human oversight remains essential for high-stakes decisions. Portfolio managers should review AI-generated valuations against their own market knowledge and require the system to explain its reasoning, why it favors one property over another, which variables drove its prediction. When the logic doesn’t hold up to scrutiny, that’s your signal to dig deeper or disregard the recommendation entirely.
Risks That Generative AI Introduces to Underwriting Decisions
Generative AI systems can introduce several distinct hazards when applied to mortgage lending and property insurance decisions, each carrying real consequences for borrowers and homeowners.
Algorithmic bias ranks among the most serious risks. AI models trained on historical underwriting data can absorb and amplify past discrimination patterns, declining mortgage applications from certain neighborhoods, assigning higher premiums based on property location correlates that mask protected characteristics, or systematically undervaluing homes in specific communities. A borrower with strong credit might face rejection not because of their actual risk profile, but because the AI learned problematic associations from decades-old lending practices embedded in its training data.
Hallucinated or fabricated data poses another significant threat. Generative AI can confidently produce plausible-sounding risk assessments based on information it essentially invented, citing property flood history that never occurred, referencing market conditions that don’t exist, or calculating neighborhood crime statistics from synthetic data rather than verified sources. An insurer relying on these false inputs might deny coverage or inflate premiums based on risks that aren’t real, while a lender could approve a loan on overly optimistic projections.
Over-reliance and deskilling creates operational vulnerabilities. When underwriters trust AI recommendations without scrutiny, they lose the expertise to catch errors or apply contextual judgment that algorithms miss. A loan officer who stops questioning why the system flagged a rural property as high-risk might overlook that the AI misclassified a septic system as a flood hazard, denying financing to a qualified buyer unnecessarily.
Regulatory and compliance violations multiply as AI makes decisions that human underwriters would recognize as problematic. Systems that inadvertently use prohibited factors, fail to provide adverse action explanations, or can’t demonstrate fair lending compliance expose institutions to enforcement actions and litigation. For real estate businesses deploying these tools, AI risk coverage has become essential protection against liability from algorithmic errors affecting clients’ property transactions and financing outcomes.
Frequently Asked Questions
Generative AI is reshaping how lenders and insurers evaluate risk, but that transformation raises legitimate questions for anyone navigating property finance. Whether you’re applying for a mortgage, shopping for homeowners insurance, or working as a real estate professional, understanding your rights and the role AI plays in these decisions matters.
Can AI deny my mortgage application without a human reviewing it?
No. Federal fair lending laws require that a qualified human underwriter review and approve or deny mortgage applications, even when AI tools assist in the evaluation process. The AI generates recommendations, but a licensed professional makes the final decision and must be able to explain the reasoning behind any denial.
How do I know if AI was used to evaluate my loan or insurance application?
You can ask your lender or insurer directly whether they use AI-powered underwriting systems. Many institutions now disclose this information in their application materials or privacy notices, though specific details about the AI model itself typically aren’t shared due to proprietary concerns.
What happens if the AI system makes a mistake in assessing my property risk?
You have the right to dispute errors in your application and request a manual review. If AI miscalculates your income, misjudges your property’s flood risk, or generates inaccurate information, the lender or insurer must investigate and correct the record, just as they would for any underwriting error.
Do I have a legal right to request a human review of an AI decision?
While specific AI review rights vary by jurisdiction, existing consumer protection laws generally allow you to request reconsideration of lending or insurance decisions. Some states are introducing explicit requirements for human oversight of automated decisions in financial services.
How is generative AI in underwriting regulated right now?
Generative AI systems must comply with existing fair lending laws, equal credit opportunity regulations, and insurance anti-discrimination statutes, even though few rules specifically address AI technology. Regulators are developing AI-specific guidance, but current enforcement focuses on outcomes rather than the technology itself.
Should I be concerned about bias in AI underwriting systems?
Responsible lenders and insurers actively test their AI models for bias and monitor outcomes across different demographic groups. However, you should review denial explanations carefully, ask questions if something seems unfair, and report potential discrimination to your state’s consumer protection agency or the Consumer Financial Protection Bureau.
These questions reflect the reality that generative AI risk management directly impacts your experience as a borrower or policyholder. The technology may be complex, but your rights remain straightforward: fair treatment, accurate information, and human accountability for decisions that affect your ability to buy, insure, or finance property.
Generative AI is reshaping how lenders evaluate mortgage applications and insurers price property coverage, but its power comes with real responsibility. Without robust risk management, these systems can perpetuate bias, generate faulty predictions, or make decisions that hurt both borrowers and institutions. That’s why understanding how your lender or insurer governs their AI tools isn’t just technical curiosity, it directly affects whether you get fair treatment, accurate pricing, and trustworthy decisions on the biggest financial commitment most people make.
As a homebuyer, real estate professional, or property investor, you have every right to ask questions. When you apply for a mortgage or property insurance, inquire about the AI systems involved: How are they tested for fairness? Who reviews the recommendations? What happens if the model makes a mistake? Lenders and insurers committed to responsible AI will welcome these conversations, not dodge them.
The technology will keep advancing. The institutions that combine innovation with transparent, accountable risk management will earn trust and deliver better outcomes. Those that don’t will face regulatory scrutiny and lose customers who demand more. Your awareness and questions help push the industry toward that better future.