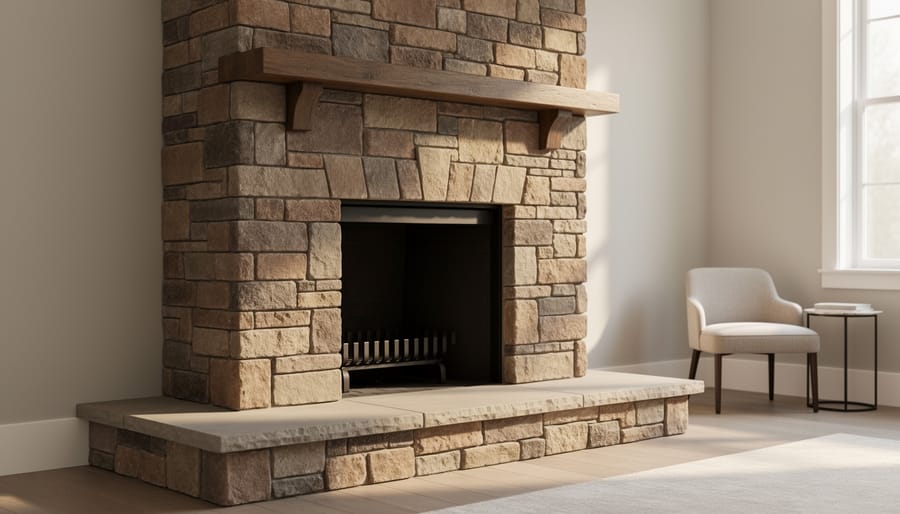
“Detailed view of a stone fireplace in a living room, highlighting the hearth and chimney opening for homebuyers to inspect before purchasing.”

Questions to Ask About a Fireplace Before Buying a Home: A Complete Guide

Before you sign closing papers on that charming home with the stone hearth, ask the seller seven critical questions about the fireplace: when was it last inspected, what type of fuel does it burn, is the flue damper functional, are there any known structural issues, what maintenance has been performed, does it comply with current building codes, and can you review service records. These questions protect you from inheriting a $3,000 to $15,000 repair bill or worse, a fire hazard that puts your family at risk.
Most homebuyers focus on square footage and curb appeal while overlooking the fireplace tucked in the corner of the living …

“Finance professional working at a desk with a laptop showing an abstract neural network glow and risk-focused underwriting documents, representing generative AI risk management.”

What Is Generative AI Risk Management (and How Does It Work in Underwriting)?

Generative AI risk management is the systematic process of identifying, assessing, and controlling the unique risks that arise when financial institutions use generative artificial intelligence models to make lending, underwriting, and insurance decisions. Unlike traditional AI systems that follow fixed rules, generative AI can create new outputs, predictions, and recommendations, which introduces uncertainty around accuracy, bias, transparency, and regulatory compliance.
For real estate professionals and property buyers, this matters more than you might expect. When a mortgage lender uses generative AI to assess your …

Homebuyer comparing home and auto insurance documents on a kitchen table with a car key and a small model house nearby.

How to Compare Home and Auto Insurance Quotes in Canada: A Step-by-Step Guide for Homebuyers

Comparing home and auto insurance quotes in Canada means gathering at least three proposals from different insurers using identical coverage limits and deductibles, then evaluating them line by line to find the best combination of price, coverage breadth, and insurer reliability. This process ensures you’re meeting provincial legal requirements while securing coverage that actually protects your assets, not just checking a compliance box.
The challenge isn’t getting quotes. Most insurers will happily provide one. The real work lies in making an apples-to-apples comparison when each proposal arrives formatted differently…

Detached Winnipeg home exterior in winter with icy roof eaves and wet street reflections near the foundation, suggesting weather and sewer backup risks.

How Much Does Home Insurance Cost in Winnipeg? (2026 Guide for New Homeowners)

Home insurance in Winnipeg costs between $1,200 and $2,500 per year for a detached home, with most homeowners paying around $1,000 annually or roughly $80 per month. If you’re shopping for coverage in Manitoba’s capital, you’ll find that your final premium hinges on four main variables: your home’s age and construction type, its replacement value, your claims history, and the coverage limits you select.
Key Takeaway: Winnipeg homeowners should budget $1,200-$2,500 annually for home insurance, carry at least $2 million in liability coverage, and ensure their policy …

Lakeside Quebec cottage at dusk with warm window lights reflecting on calm water, representing a second home property setting.

How Much Do Second Home Mortgage Rates Cost in Quebec? (2026)

Mortgage rates for second homes in Quebec currently start at 4.04% for insured five-year fixed terms and 3.40% for five-year variable rates, according to daily pricing from banks and mortgage brokers tracked by Ratehub as of mid-August 2026. But here’s what most buyers don’t realize upfront: those baseline numbers rarely apply to vacation properties or investment cottages the way they do to primary residences.
Second-home financing almost always costs more than your main residence mortgage. Three factors drive that premium: lenders consider non-primary properties higher risk, down payment requirements are typically …

Real estate professional in a modern office with subtle glowing mitochondrial energy motifs representing metabolic signaling.

MOTS-c Peptide: What It Is, How It Works, and Why Real Estate Professionals Should Care

MOTS-c is a mitochondria-derived peptide that signals cells to improve metabolic function, insulin sensitivity, and energy production. Discovered in 2015, this 16-amino-acid peptide is encoded within mitochondrial DNA and acts as a metabolic regulator, essentially telling your body to burn fuel more efficiently and resist age-related metabolic decline.
Unlike most peptides that originate from nuclear DNA, MOTS-c comes from the powerhouse of the cell itself. When mitochondria detect metabolic stress or aging, they release this peptide into the bloodstream, where it travels to …

Homeowner holding an insurance claim folder in a partially repaired living room with visible damage near a window and repair materials in the background.

Does an Insurance Payout Count as Income? What Homeowners and Real Estate Pros Need to Know

An insurance payout counts as income only when it exceeds the actual loss or damage you incurred. In most property-related situations, whether it’s a fire, flood, or storm claim on your home or rental property, the money you receive from your insurer simply restores what you lost and carries no tax liability. The taxable income question arises in specific scenarios: when the payout exceeds your adjusted basis in the damaged property, when you receive business interruption or rental income replacement payments, or when you’re compensated for lost profits rather than physical damage.
Understanding whether …

Mortgage documents and a key held in front of a suburban home, with blurred lender paperwork in the background to represent a release clause concept.

What Is a Release Clause in a Mortgage (and How Does It Work)?

A release clause in a mortgage is a contractual provision that allows specific portions of collateral property to be released from the lender’s lien once certain conditions are met, typically a partial loan payoff or insurance settlement. For property owners who’ve financed land development, multi-parcel purchases, or properties that later suffer partial damage, this clause becomes the mechanism that unlocks insurance proceeds or permits the sale of individual lots without retiring the entire mortgage balance.
The stakes are particularly high when insurance money enters the picture. After a fire, storm, or other insured …

Construction site with steel beams and timber bundles in the foreground, suggesting ethical supply-chain risk for real estate development and financing.

What Are Ethical Issues in Supply Chain Management (and How Do They Impact Real Estate and Finance)?

Ethical issues in supply chain management encompass the labor rights violations, environmental damage, corruption, and human rights abuses that can occur at any stage of producing and delivering goods and services. For real estate developers, lenders, and insurers, these issues translate directly into project delays, regulatory fines, reputational damage, and significant financial exposure when materials sourcing or contractor practices fail to meet ESG standards.
The stakes have never been higher. Construction materials like steel, concrete, and timber often originate from supply chains with documented concerns around forced labor…

A homebuyer and insurance broker meet in a living room over an open binder, conveying personalized home insurance guidance in Calgary.

How to Choose a Home Insurance Broker in Calgary: A Homebuyer’s Guide

Finding the right home insurance broker in Calgary takes three essential steps: verify their Alberta insurance license, confirm they represent multiple insurers (not just one), and ask specific questions about replacement cost coverage for your property’s unique risks. A qualified broker saves you money and protects your investment by comparing policies across carriers, something captive agents and direct insurers can’t offer.
Calgary’s real estate market in 2026 presents distinct challenges. Hailstorms cause millions in property damage annually, and the city’s mix of older character homes and new …